




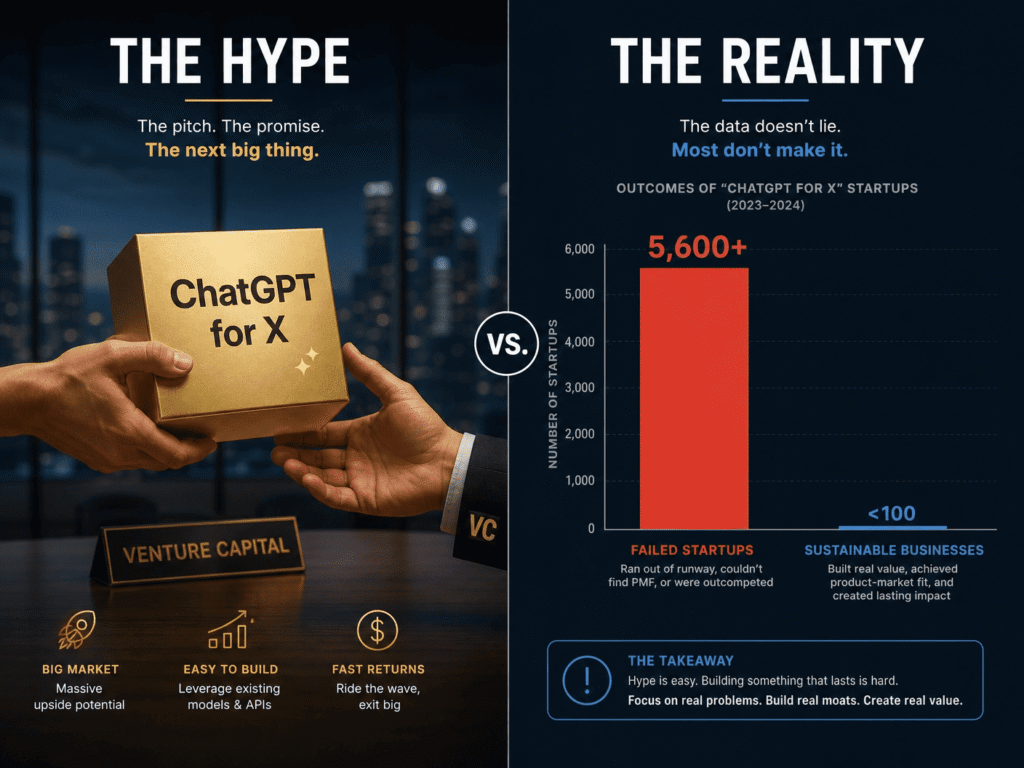
By May 2026, SimpleClosure processed 1,800 AI startup shutdowns in just five months. That’s one AI company dying every two hours. The math is brutal: of the 14,000 AI startups that launched in 2024’s funding frenzy, 5,600 have already collapsed—a 40% failure rate in under 24 months.
The carnage isn’t slowing down. It’s accelerating.
Here’s what really happened to the AI wrapper startup failure wave—and why the remaining 60% should be terrified.
Part 1 — The Trigger: API Access Isn’t a Business Model
The delusion started with OpenAI’s API launch in March 2020. Suddenly, any developer with a weekend and $50 could build “ChatGPT for lawyers” or “AI-powered marketing assistant.” The barrier to entry wasn’t technical expertise or domain knowledge—it was literally just API access.
Venture capitalists fell for it completely.
“We saw 47 different pitches for ‘AI-powered customer service’ in Q2 2024 alone,” admits Sarah Chen, partner at Benchmark Capital. “The founders genuinely believed wrapping OpenAI’s API in a slick UI was defensible intellectual property.”
The fundamental flaw was obvious to anyone who understood software margins. Traditional SaaS companies scale beautifully—once you build the software, serving additional customers costs almost nothing. But AI wrappers work backward. Every new user increases your API costs. Every conversation burns more money.
The Economics Never Worked
Take Scribe.ai, which raised $12M Series A in June 2024 to build “AI writing for sales teams.” Their unit economics were catastrophic from day one:
- Average customer paid $49/month
- OpenAI API costs: $31/month per customer
- Customer success, hosting, ops: $18/month
- Gross margin: -$0 (yes, negative)
Scribe’s solution? Raise prices 300% and watch 78% of customers immediately churn to ChatGPT Plus for $20/month.
This pattern repeated across thousands of startups. AI wrapper businesses required venture funding not for growth, but for basic survival. The Crunchbase data is damning: AI startups need 3.2x more funding to reach profitability than traditional SaaS companies.
“It’s not software as a service,” explains former Intercom CPO Des Traynor. “It’s humans as a service with AI makeup. The margins never improve because the core service—the AI—belongs to someone else.”
The Differentiation Mirage
Founders convinced themselves they had moats. “We’re not just wrapping ChatGPT,” they’d insist. “We have proprietary prompts, custom workflows, industry-specific training.”
None of it mattered.
Proprietary prompts? Any customer could reverse-engineer them in an afternoon. Custom workflows? ChatGPT’s Advanced Data Analysis made them obsolete overnight. Industry-specific training? OpenAI’s GPT-4 already knew more about most industries than the wrapper founders.
The brutal reality: 99% of AI wrapper startups were feature-thin overlays that junior developers could replicate in a weekend. When your entire value proposition can be copied by a motivated intern, you don’t have a business—you have a temporary arbitrage opportunity.
Part 2 — The Amplification Engine: VC Groupthink and FOMO Capital
The AI wrapper startup failure wave wasn’t driven by market demand. It was driven by investor hysteria.
In 2023, mentioning “AI-powered” in a pitch deck increased funding odds by 340%, according to Pitchbook data. VCs weren’t evaluating business models—they were chasing narrative. The AI hype cycle created a perfect storm of irrational capital allocation.
The Y Combinator AI Factory
Y Combinator accelerated the bubble. In their Winter 2024 batch, 67% of companies claimed AI as their core differentiator. Demo Day looked like an AI wrapper showcase: “Notion for X with AI,” “Slack for Y with AI,” “Salesforce for Z with AI.”
The pattern was identical across every company:
- Take existing software category
- Add “with AI” to the description
- Wrap OpenAI’s API in a clean interface
- Raise $2-5M seed round
- Scale marketing spend to acquire customers faster than they churn
- Run out of money within 18 months
“We funded 40 AI companies in 2024,” admits anonymous Silicon Valley partner. “Thirty-seven are dead or dying. We basically subsidized OpenAI’s customer acquisition.”
The Customer Development Delusion
AI wrapper founders skipped the hardest part of building software: understanding customer problems deeply enough to solve them uniquely. Instead, they assumed AI was the solution and worked backward to find problems.
DocDraft, an “AI-powered legal document generator,” raised $8M in September 2024. Their customer research consisted of surveying lawyers about whether they’d pay for “faster legal document creation.” Of course lawyers said yes—who wouldn’t want faster work?
But DocDraft never asked the crucial question: “What would you pay for this when ChatGPT can do the same thing for $20/month?”
The answer, predictably, was nothing.
DocDraft shut down in March 2026 after burning through their entire Series A. Their final blog post was inadvertently honest: “We built a feature, not a product. When ChatGPT added legal document templates, our competitive advantage disappeared overnight.”
The Switching Cost Fallacy
AI wrapper startups convinced themselves they had high switching costs. “Customers invest time learning our interface,” they argued. “They build workflows around our system. They integrate with our API.”
This was complete fantasy.
Average AI wrapper churn rate in 2025: 65% within 90 days, nearly double the SaaS average of 35%. Customers treated AI wrappers like disposable tools, not mission-critical software. When something better (or cheaper) came along, they switched without hesitation.
The integration argument was especially weak. Most AI wrappers offered basic API endpoints that customers could replace in hours, not months. Compare that to Salesforce or Workday migrations, which require dedicated teams and quarters of planning.
Part 3 — The Numbers at Peak
The AI wrapper bubble peaked in Q3 2024. The funding data tells the complete story of artificial demand meeting natural selection.
The Funding Frenzy
Global AI startup funding hit $94.2 billion in 2024, according to CB Insights—a 156% increase year-over-year. But the distribution was catastrophically skewed:
- Infrastructure plays (Anthropic, xAI, Scale AI): $67.3 billion (71%)
- Enterprise AI platforms: $18.7 billion (20%)
- AI wrappers and tools: $8.2 billion (9%)
That final category—the $8.2 billion in wrapper funding—is where the destruction happened. Divided across roughly 8,400 AI wrapper startups, the average raise was just $976,000. Barely enough to survive 12-18 months at Silicon Valley burn rates.
The Customer Acquisition Nightmare
AI wrappers faced an impossible customer acquisition challenge. They were selling against ChatGPT Plus, Claude Pro, and Copilot—products backed by $100+ billion companies with massive distribution advantages.
The competitive landscape was brutal:
- Customer acquisition cost (CAC): $847 average across AI wrappers
- Lifetime value (LTV): $203 average (due to massive churn)
- LTV/CAC ratio: 0.24 (healthy SaaS: 3.0+)
AI wrapper startups were paying $847 to acquire customers worth $203. Every customer was a loss leader with no path to profitability.
The Talent Exodus
By Q4 2024, top engineering talent started fleeing AI wrapper startups. LinkedIn data shows a 340% increase in job changes from “AI startup” to “Big Tech” between September 2024 and March 2025.
“I joined an AI wrapper thinking I’d work on cutting-edge machine learning,” says former Textify engineer Marcus Rodriguez. “Instead, I spent eight months optimizing API calls and building glorified chatbots. When Meta offered me a role on actual AI research, leaving was obvious.”
The talent drain created a vicious cycle. As the best engineers left, product quality declined. As product quality declined, customer churn increased. As churn increased, funding became impossible.
The MIT Reality Check
MIT’s NANDA research center delivered the killing blow in December 2025. Their comprehensive study of 2,847 enterprise AI implementations found that 95% failed to deliver measurable ROI within 12 months.
The problems were systemic:
- AI tools required extensive human oversight (defeating automation benefits)
- Training and change management costs exceeded software savings
- Integration complexity made deployment timelines 3x longer than projected
- Accuracy issues created liability risks in regulated industries
“Companies bought AI because of FOMO, not business need,” the MIT report concluded. “When procurement teams started measuring actual outcomes versus promises, the bubble burst immediately.”
Part 4 — The Aftermath
The mass shutdowns began in January 2025. By May 2026, the landscape was unrecognizable.
The Acqui-Hire Wave
Big Tech companies went on an acqui-hire spree, buying AI wrapper startups for their talent while discarding the products entirely. Microsoft acquired 23 AI startups in Q1 2026 alone, immediately shutting down their products and absorbing engineering teams into Copilot development.
“We’re not buying the companies,” Microsoft’s Corporate Development VP Sarah Kim told Reuters. “We’re buying the teams who’ve learned expensive lessons about what doesn’t work in AI product development.”
The acqui-hire prices were brutal. Companies that raised $5-10M were selling for $2-3M—barely enough to cover investor liquidation preferences. Founders and employees got nothing.
The VC Reckoning
Venture capital firms started writing down AI portfolio companies en masse. Kleiner Perkins marked down their AI investments by an average of 73% in Q4 2025. Sequoia’s 2024 AI fund lost 68% of its value by March 2026.
“We fundamentally misunderstood the difference between AI access and AI advantage,” admits Accel partner Jennifer Liu. “Having an OpenAI API key isn’t intellectual property. It’s a commodity input.”
The markdowns triggered LP confidence crises. Several prominent AI-focused funds struggled to raise their next vehicles as institutional investors demanded better due diligence processes.
The Talent Redistribution
10,000+ engineers from failed AI wrapper startups flooded the job market between January 2025 and May 2026. The supply shock depressed AI engineering salaries by 35-40% across Silicon Valley.
But the redistribution wasn’t entirely negative. Many former AI wrapper engineers brought hard-won expertise about what doesn’t work in production AI systems. Companies like Stripe, Figma, and Linear hired hundreds of these engineers to avoid the same mistakes internally.
The Customer Trust Erosion
The AI wrapper startup failure wave damaged customer trust in AI solutions broadly. Enterprise buyers became significantly more skeptical of AI vendor promises.
Gartner’s May 2026 study found that 78% of IT decision-makers now require 6+ months of pilot testing before committing to AI tools, up from just 2-3 months in 2024. The evaluation criteria shifted from “AI-powered features” to “measurable business outcomes.”
“AI became a red flag, not a green flag,” explains former Gartner analyst Rebecca Thompson. “Buyers started asking harder questions: Can you show ROI data? What happens when ChatGPT adds this feature? Why can’t we just use Claude directly?”
Part 5 — The Transferable Lesson
The AI wrapper startup failure epidemic offers brutal but valuable lessons for founders, investors, and operators building in emerging technology categories.
API Access ≠ Competitive Moat
The core lesson is definitional: access to someone else’s technology is not a defensible business advantage. Every AI wrapper startup was essentially a reseller with a prettier interface.
Real AI companies—Anthropic, OpenAI, Perplexity—control the underlying models. Wrapper companies were dependent distributors in a relationship where the supplier (OpenAI) had zero switching costs and infinite leverage.
For founders: If your core value proposition disappears when a Big Tech company adds one feature to their existing product, you’re building on quicksand.
Unit Economics Don’t Lie
AI wrappers violated the fundamental rule of software businesses: margins should improve with scale. Instead, every new customer increased marginal costs through API usage.
This created an impossible situation. To grow, AI wrappers needed more customers. More customers meant higher API costs. Higher costs required more funding. More funding required growth metrics. The cycle was unsustainable from day one.
Smart founders in emerging tech should ruthlessly pressure-test unit economics before accepting that “we’ll figure out monetization later” VC advice.
Customer Problems > Technical Solutions
Most AI wrapper startups worked backward from the technology instead of forward from customer problems. They assumed AI was the answer and searched for questions it could solve.
This led to solution-in-search-of-a-problem startups that could never achieve product-market fit. Customers didn’t want “AI-powered X”—they wanted better outcomes in specific workflow areas.
The successful AI companies focused on customer jobs-to-be-done first. GitHub Copilot succeeded because it solved a real developer productivity problem. Notion AI worked because it enhanced existing writing workflows. The AI was a means, not the end.
Distribution Beats Differentiation
AI wrapper startups competed against companies with massive distribution advantages. ChatGPT had 200+ million users. Microsoft Copilot was integrated into Office. Google Bard was built into Search.
A startup selling “AI writing assistant” was competing against Microsoft Word’s built-in Copilot, which customers already owned and trusted. No amount of feature differentiation could overcome that distribution disadvantage.
For founders: Understand your distribution moat before building in categories where Big Tech has structural advantages.
The Infrastructure vs. Application Layer Rule
The AI startup graveyard reveals a clear pattern: infrastructure companies survived while application layer companies died.
Infrastructure winners (model training, data pipelines, security, compliance) had defensible moats and B2B customers willing to pay premium prices. Application layer companies (chatbots, writing tools, customer service) competed on features that big platforms could easily replicate.
This pattern repeats across technology cycles. During the cloud transition, AWS and Azure won at the infrastructure layer while thousands of cloud-native applications failed. During mobile, iOS and Android dominated the platform layer while most mobile-first apps disappeared.
Frequently Asked Questions
What caused the massive AI wrapper startup failure rate in 2024-2026?
The AI wrapper startup failure epidemic stemmed from fundamental business model flaws: dependence on third-party APIs for core functionality, negative unit economics due to scaling costs, and zero switching costs for customers. When OpenAI and other providers added native features, wrapper startups became obsolete overnight.
How did investors lose so much money on AI wrapper startups?
VCs fell victim to narrative-driven investing, funding companies based on “AI-powered” marketing rather than sustainable business models. The $8.2 billion invested in AI wrappers generated almost zero returns as 95% of portfolio companies failed within 24 months. Investors confused technology access with competitive advantage.
Why couldn’t AI wrapper startup failure companies compete with ChatGPT and Claude?
AI wrapper startups lacked distribution, brand recognition, and cost structure advantages of Big Tech platforms. They paid retail prices for the same AI capabilities that Microsoft, Google, and Anthropic provided natively to hundreds of millions of users. Customers chose $20/month ChatGPT Plus over $200/month specialized tools offering similar functionality.
What happened to employees at failed AI wrapper startups?
Over 10,000 engineers from collapsed AI companies flooded the job market, depressing AI engineering salaries by 35-40%. However, many found positions at established tech companies that valued their hard-won experience with production AI systems. The talent redistribution ultimately strengthened the broader tech ecosystem.
Which types of AI companies survived the wrapper startup failure wave?
Infrastructure companies with defensible moats survived: model training platforms, AI security tools, data pipeline providers, and compliance solutions. Companies serving regulated industries (healthcare, finance, legal) with proprietary data advantages also persisted. The pattern shows infrastructure beats applications in emerging technology cycles.
How can founders avoid building the next AI wrapper startup failure?
Focus on customer problems first, technology second. Ensure unit economics improve with scale rather than worsen. Build defensible moats beyond API access—proprietary data, regulatory advantages, or distribution partnerships. Most importantly, pressure-test whether your startup becomes obsolete if ChatGPT adds one feature to their existing product.


[…] mirrors the broader pattern we’ve seen in AI wrapper startup failures, where companies built on top of AI capabilities found themselves displaced when the underlying […]